
IntroductionWorking on sustainability is key. Governments are introducing laws to encourage responsible behavior in this area. In this blog, we discuss the European Commission's Corporate Sustainability Reporting Directive (CSRD) and European Sustainability Reporting Standards (ESRS). We take you through how to operationalize this sustainability reporting efficiently and effectively. The reason for the introduction of CSRD and the ESRS is implementation of the 2015 Paris Climate Agreement by the European Union and all member states. In this blog, we address the questions below:
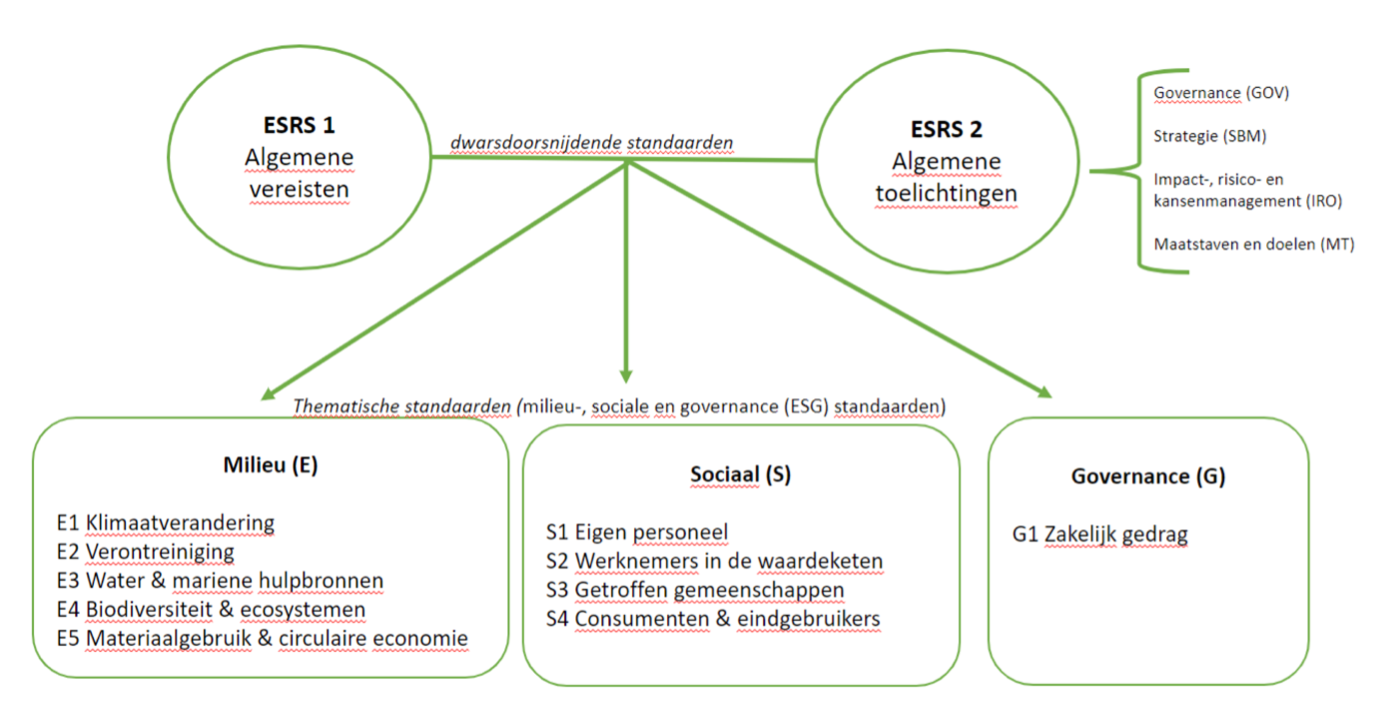 ESRS adopted and mandatory (EU delegated legislation) on June 30, 2023 consist of:
- What is the CSRD and the ESRS?
- What goals is the EU pursuing with the CSRD and ESRS?
- Do the CSRD and the ESRS apply to my organization?
- What are the requirements?
- Efficient implementation and demonstrable mastery of sustainability requirements
ESRS adopted and mandatory (EU delegated legislation) on June 30, 2023 consist of:
- The ESRS 1 contains an explanation of the general reporting requirements. It is important to read it carefully so that the concepts (including dual materiality) become clear.
- The ESRS 2 contains 16 concrete general reporting requirements that must be followed by the organization. These requirements cover reporting principles, governance, strategy, impact, risk and opportunity management, and metrics and targets.
- The ESRS E1 contains 12 concrete reporting requirements related to climate change and are related to the requirements from the ESRS 2.
- The ESRS S1 contains 19 concrete reporting requirements related to its own personnel, and these requirements are also related to those in the ESRS 2.
- Shifting capital flows from the gray to the green economy. Among other things, to get investors and banks to invest more in companies making the transition to sustainable operations or start-ups with green/circular products.
- Make sustainability an integral part of risk management. This puts sustainability into a company-wide PDCA cycle.
- Encourage transparency (unambiguous) and long-term thinking. This is reflected in sustainability reporting that makes companies more comparable. This enables investors and financiers to make better decisions on what to invest their money in.
- Starting Jan. 1, 2024, large public-interest companies (more than five hundred employees) already covered by the current Non-Financial Reporting Directive (NFRD) will have to deal with preparing these reports in 2025 for the previous fiscal year.
- From Jan. 1, 2025, large companies not yet covered by the Non-Financial Reporting Directive (NFRD) (2 out of 3: more than 250 employees and/or €40 million in sales and/or €20 million in total assets) will have to deal with preparing these reports in 2026 for the previous fiscal year.
- As of Jan. 1, 2026, listed SME companies will face these reports in 2027 for the previous fiscal year.
- Determine which employees are or will be working on sustainability and what tasks, responsibilities and authority they have. Read up on and follow publications from, for example, industry associations and reports from other organizations. Tip: especially look at publications on the SER website (CSRD and the ESRS: questions and answers). A useful and readable report on sustainability can be found on Zeeman's website(https://www.zeeman.com/media/wysiwyg/pdf/MVO_verslag_2021.pdf).
- Map your organization and context and engage with your stakeholders. Aim to do a dual materiality analysis.
- Take stock of what you are already doing on sustainability and what is still needed from the obligations of the CSRD and the ESRS (gap analysis).
- Set policy for sustainability. Answer where you want to be in 3 years and how to get there (Plan of Action).
- Implement a framework to achieve demonstrable compliance. Ensure that this framework provides accurate and up-to-date information and a strong PDCA cycle to remain in compliance with the CSRD and ESRS.
- Collect sustainability data. Determine what data is relevant, how reliable it is and what information is still missing.
- Compile an initial report and discuss it with your accountant to determine where improvements are needed.

Perium scores an 8.5 in a customer satisfaction survey
Perium scores an 8.5 in a customer satisfaction survey and is committed to customer-driven innovation. In its recent customer satisfaction survey, Perium received an impressive score of 8.5. The

Perium integrates the updated NEN7510:2024 standard into its platform
The latest version of the NEN7510 standard for information security in healthcare is now fully available within the Perium platform. The revision of the standard, which was published in

Perium is a member of Samenwerking Noord
We are proud to share that we have joined Collaboration North 🤩 Collaboration North connects public and private organizations around IT and digitalization, with